
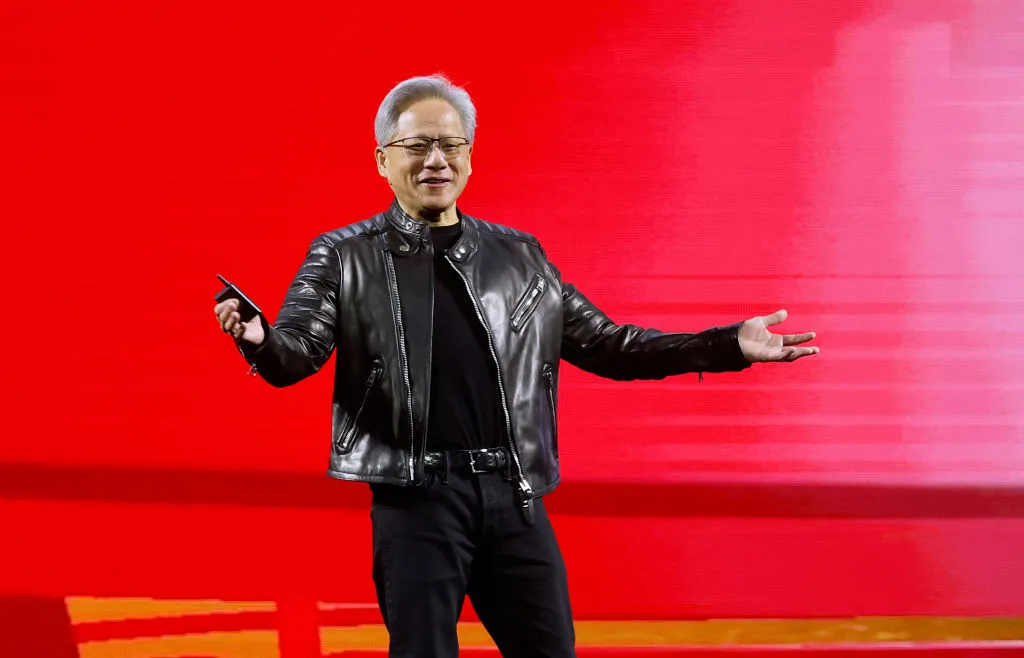
Nvidia’s stock slid more than 4% on Monday, the first trading day after its board said it would investigate CEO Jensen Huang over his relationship with Alice Huang, an executive U.S. intelligence believes was spying for China.
Securities lawyers were already moving. At least four firms, including Schall, Brown & Schwartz and Levi & Korsinsky, announced investigations Monday into whether Nvidia misled investors. Robert Bartlett, a Stanford Law professor and securities law expert, expects them to have plenty of company.
“I would definitely wager that there’ll be a filing,” Bartlett said in an interview Monday morning, adding that he wouldn’t be surprised if a case had been filed by the end of the day. Plaintiffs’ lawyers have good reasons to be first in line; under federal securities law, the first complaint triggers a public notice, and investors then have 60 days to ask the court to be named lead plaintiff. A firm that files early gets a head start on signing up investors with large losses, as well as on shaping the story of the case. Bartlett was right, in fact. A case surfaced Monday afternoon in the Northern District of California, where Nvidia is headquartered.
Rosen Law Firm, a New York-based plaintiffs’ firm that specializes in securities class actions, filed it on behalf of Mark Kistenmacher, a retail investor who made seven purchases totaling roughly $20,500 this year, according to a schedule attached to the complaint. (Rosen was lead counsel in a $250 million settlement with Alibaba and ranks among the most active filers of such cases.) The proposed class covers anyone who bought Nvidia securities between Oct. 9, 2025, and Nov. 8, 2026, and the suit names both Nvidia and Huang.
The complaint accuses them of misleading investors about Huang’s ties to Megaspeed, the Singapore-based data center outfit where Alice Huang was considered a top exec, and it points to three statements as proof: Nvidia spokesperson John Rizzo’s late-October claim that Huang’s interactions with Alice Huang were “not unusual or unexpected,” the company’s even earlier claim that it found “no evidence of diversion” of its chips, and Jensen Huang’s Oct. 30 comment to Bloomberg that Nvidia’s dealings with Megaspeed were “normal and not unusual.”
All three were false or misleading, the suit says, because Huang was having an affair with Alice Huang. Kistenmacher is asking for unspecified damages, interest and attorneys’ fees, and he wants a jury trial.
While much remains unknown, the legal theory here doesn’t depend on anything the board’s investigation may turn up about Huang’s private life. When The New York Times first reported on Huang’s ties to Alice Huang last month, Rizzo really did tell the Times that the relationship was “not unusual or unexpected.” Rizzo separately told another outlet, The Hill, that “Megaspeed has been no different than many other regional cloud customers. Meetings with customers are part of a CEO’s job; Jensen talks with thousands of customer executives every year.”
Since then, Huang has acknowledged to the board that the relationship was intimate. Meanwhile, The Times reports that U.S. intelligence had been monitoring Alice Huang for more than a year.
From a securities perspective, Bartlett said, the company’s earlier statement was “clearly a misleading statement.” And because Huang is CEO, Bartlett said, “his knowledge gets imputed to the company.” In other words, Nvidia is treated as having known what its chief executive knew.
The Kistenmacher complaint makes the same argument.
Bartlett predicted a “classic fraud on the market” claim, in which investors argue they paid prices that reflected false or incomplete public information, and lost money when the truth emerged. This early lawsuit relies on that theory, and Monday’s drop of $7.97 per share, or 4.27%, gives the attorneys involved a lot to work with. Damages in such cases are tied to the stock’s decline, and Nvidia is one of the most valuable companies in the world, so you can imagine a settlement could prove exceedingly expensive.
The usual path is that the case is litigated for a long time and then settles, Bartlett notes. That means a large payment from the company and its directors-and-officers insurers, but typically no personal consequences for the CEO or the board. It is also a civil matter, so Huang isn’t facing prison over it.
The irony, as Bartlett noted, is that the suit is brought in the name of Nvidia’s shareholders, and shareholders ultimately pay for the settlement, directly or through insurance premiums.
Bartlett sorted Nvidia’s wider exposure into buckets. The first is the securities fraud claim, which is the clearest immediate problem for the company and potentially for Huang. The second is governance: what the board knew and when. It’s possible directors were kept in the dark, but the board also has oversight duties, and once the Times began reporting on the Megaspeed connection, the company should have had reporting lines to bring a critical risk like this to directors. If it didn’t, or if directors didn’t act, board-level liability is possible.
A third category, one that would change everything, would arise only if the board’s investigation finds Huang knew about the intelligence connection. That would be “a whole other ball game,” as Bartlett said. (The board said in a statement to the public Sunday that it has no reason to believe national security or Nvidia secrets were compromised.)
There’s also the question of government action. The SEC can seek an officer-and-director bar for intentional securities-fraud violations, which Bartlett said is technically on the table. But he doubts the current SEC under Chairman Paul Atkins would have the appetite, given President Trump’s support for Huang. A roughly two-year clock after discovery of the facts would leave room for a future administration to act, but the window would be tight, and Bartlett posited that’s pretty unlikely when asked about it.
It’s worth underscoring that neither law firm announcements nor this newly filed complaint is a sign of a strong case. Plaintiffs’ firms are quick to publish these notices when they see an opportunity. Which firm winds up leading the case is decided later by the court, and that decision usually depends on which investor has suffered the biggest loss. Kistenmacher said in his filing that he’s willing to serve as lead plaintiff, but the court will ultimately choose among the competing investors. No doubt they’ll materialize soon.
When you purchase through links in our articles, we may earn a small commission. This doesn’t affect our editorial independence.